
Fintech Website Design Canada: The UX and Trust Blueprint
Master fintech website design in Canada. Discover how high-converting UX, regulatory compliance, and secure portal architecture drive customer acquisition.
Published
Why Read This?
and skeptical of challengers.
Canadian consumers maintain an ironclad allegiance to the Big Six chartered banks, holding over ninety percent of domestic banking assets in institutions that have operated for over a century. When a retail investor, small business owner, or borrower arrives at an alternative digital financial platform, their default psychological posture is skepticism. Unlike standard software-as-a-service products where a user risks only an email address and a temporary password during a free trial, a financial application demands their Social Insurance Number, real-time banking credentials, and liquid capital. A single visual glitch, misaligned typography on mobile, an ambiguous security disclaimer, or a lagging KYC verification screen instantly signals fraud or insolvency. For growth-stage challengers, building an institutional-grade digital presence is not simply an aesthetic preference; it is the ultimate determinant of customer acquisition efficiency and balance sheet viability.
In this market, customer acquisition costs in search and paid social routinely exceed three hundred dollars per funded account. Leaking qualified prospects midway through an onboarding funnel because of clumsy data entry or hidden disclosures turns venture capital into fuel for competitor growth. High-performing digital platforms treat interface design, regulatory compliance, and engineering architecture as a unified discipline. This strategic blueprint examines how to build, secure, and scale modern financial platforms using sophisticated fintech website design in Canada to convert cautious visitors into loyal, verified account holders.
The Strategic Reality of Financial Services UX Design in Canada
To design an effective financial interface in Canada, product leaders and marketers must understand the unique risk profile of the domestic market. Canadian consumers are statistically less likely to switch primary financial institutions than their peers in the United Kingdom or the United States. Open banking, officially known as Consumer-Driven Banking, is developing methodically under federal oversight, which means consumers are not yet universally accustomed to frictionless, account-to-account credential sharing. Every step toward financial decentralization requires conscious user education and overt psychological reassurance.
At the same time, the regulatory landscape has entered an aggressive era of modernization. The Retail Payment Activities Act, supervised by the Bank of Canada, mandates institutional operational risk management and payment transparency for non-bank payment service providers. Provincially, Quebec's Law 25 has fundamentally altered digital privacy, introducing strict opt-in consent protocols and substantial penalties for improper personal data profiling. Federal standards under the Personal Information Protection and Electronic Documents Act require plain-language justifications for every captured data point.
When your growth strategy relies on Canadian fintech web development, compliance cannot sit in a legal silo while design teams experiment with frictionless growth hacks. If compliance requirements are tacked on after designing a user journey, the result is an awkward patchwork of legal disclaimers, abrupt third-party authentication redirects, and invasive permission banners that send conversion rates plummeting. Sustainable growth occurs when security architecture and legal mandates become core design elements that actively communicate stability, safety, and legitimacy.
Overcoming the Big Six Trust Moat with Trustworthy Web Design in Canada
Dominant incumbents like RBC, TD, and Scotiabank do not need to prove they will exist tomorrow. Challengers, whether offering neo-banking, alternative lending, algorithmic wealth management, or cross-border payment rails, must prove institutional resilience within the first five seconds of user engagement. Trustworthy web design in Canada requires replacing generic digital aesthetics with hyper-localized, legally verified, and contextually timed trust signals.
```
++
| CANADIAN FINTECH TRUST STACK |
++
| 1. LOCALIZED ANCHORS: Explicit CAD currency, Interac integration, bilingual UI |
| 2. TRANSPARENT FIDUCIARY CUES: CDIC/CIPF clarity (no misleading pass-through claims) |
| 3. CONTEXTUAL JUSTIFICATION: Inline micro-copy explaining WHY data is required |
| 4. PROGRESSIVE VERIFICATION: Experience product value BEFORE heavy KYC payload |
| 5. DECOUPLED SECURITY ARCHITECTURE: Edge-rendered static front-end + isolated portal |
++
```
Eliminating Ambiguity Around Deposit Insurance and Investor Protection
One of the fastest ways to trigger regulatory sanctions and destroy consumer credibility is the misrepresentation of deposit insurance. Challengers frequently partner with schedule one banks to hold customer deposits, but marketing teams often create misleading copy by claiming their app is Canadian Deposit Insurance Corporation insured. The CDIC strictly regulates advertising practices. If eligibility is pass-through, the interface must explicitly explain that funds are held in trust at a CDIC-member institution, subject to specific coverage limits and conditions.
Similarly, investment platforms operating under Canadian Investment Regulatory Organization guidelines must clearly state member relationships and Canadian Investor Protection Fund coverage without implying that speculative assets enjoy government-backed guarantees. High-converting designs place interactive, educational tooltips directly beside tier breakdowns or interest yield displays. By demystifying regulatory protection mechanisms instead of obscuring them in tiny footer text, the platform presents itself as an honest, mature operator worthy of institutional trust.
Hyper-Local Payment and Identity Cues
Canadian financial habits are defined by domestic infrastructure that international UI templates frequently ignore. Platforms that fail to prominently display native settlement mechanisms like Interac e-Transfer, Interac Verified, and domestic electronic funds transfers introduce immediate friction. When a user sees an interface prioritizing unfamiliar foreign payment networks or ambiguous credit card processing, their suspicion spikes.
Highlighting integration with domestic data aggregators like Flinks or certified Canadian connections through Plaid confirms the platform is fully integrated with our native clearing systems. Displaying dual-currency clarity, explicitly designating Canadian dollar balances alongside real-time exchange margins, eliminates the hidden fee anxiety that routinely drives potential users to abandon digital currency and cross-border platforms.
Friction Versus Compliance: Optimizing KYC and AML Onboarding Funnels
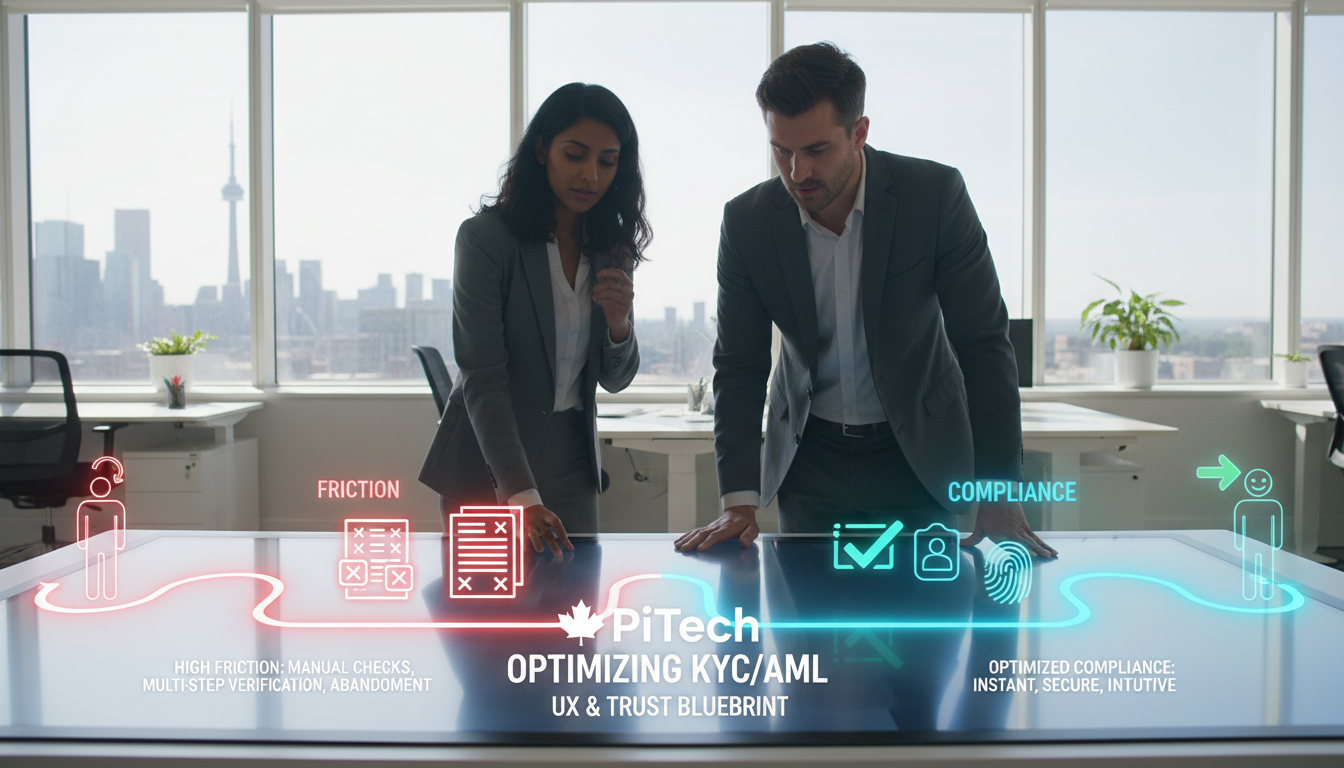
Financial onboarding is fundamentally different from typical software registrations. Under Financial Transactions and Reports Analysis Centre of Canada regulations, anti-money laundering and Know-Your-Customer mandates require capturing high-risk identification markers. These include legal names, residential addresses verified against credit bureaus, employment details, and Social Insurance Numbers.
In a standard conversion funnel, every additional form field reduces completion rates by a measurable percentage. In financial services UX design, demanding sensitive data prematurely can drop conversion rates to near zero. Solving this problem requires shifting from monolithic registration forms to progressive disclosure and psychological reciprocity.
```
TRADITIONAL ONBOARDING FUNNEL (HIGH DROPOFF)
[Landing Page] -> [Full KYC Form + SIN Capture] -> [Identity Drop-off 78%] -> [Portal Access]
PROGRESSIVE PROFILING FUNNEL (HIGH CONVERSION)
[Value Landing Page] -> [Low-Friction Account Creation] -> [Interactive Value Discovery]
-> [Contextual KYC Micro-Steps] -> [Secure Document Verification] -> [Funded Account]
```
The Architectural Strategy of Progressive Profiling
Never ask for a Social Insurance Number or photo identification on the first three screens of an onboarding flow. High-converting platforms initiate the user journey with low-friction commitments: an email address, a password, and a biometrically protected passkey. Once the user establishes an account, the interface should immediately guide them through value discovery.
Allow users to configure their investment portfolio, calculate their mortgage pre-qualification limit, or customize their corporate expense management dashboard before requesting regulatory compliance payloads. When a user has invested three minutes shaping their prospective financial environment, their psychological commitment to completing identity verification increases dramatically. At that stage, introducing FINTRAC-mandated verification fields feels like a logical, protective security measure rather than an intrusive barrier.
Micro-Copy as a Conversion Driver for High-Sensitivity Fields
When sensitive data collection becomes legally mandatory, the interface must provide immediate, contextual justification directly adjacent to the input field. Do not rely on external links to thirty-page privacy policies. High-performing financial forms employ persistent, inline helper micro-copy that explicitly addresses the user's unstated fears.
When capturing a Social Insurance Number, the form should clarify right below the input field that the Canada Revenue Agency requires this number for tax reporting purposes and that the platform will never run a hard credit check without explicit, secondary consent. When requesting government-issued photo identification through automated identity capture APIs such as Persona or Trulioo, provide clear visual guides showing how images are encrypted in transit and deleted from third-party server caches. Transforming legal obligations into transparent, educational interactions is the foundational principle of fintech conversion rate optimization.
Dynamic Verification Routing to Minimize Verification Bottlenecks
Not every user profile requires the same level of verification friction. Modern platforms implement dynamic routing based on progressive risk scoring. If an applicant's initial data attributes can be validated instantaneously against Canadian credit bureau records using soft credit pulls, bypass manual document submission entirely.
If an identity verification check fails due to a recent change of address or an ambiguous credit history, avoid displaying a generic verification failed error message. Dead ends devastate user retention. Instead, dynamically adapt the interface to offer an alternative verification path, such as an instant bank verification hook via open banking APIs, or allow the user to schedule an asynchronous document review while retaining access to read-only platform features.
Navigating Canadian Compliance by Design: PIPEDA, Law 25, and AODA
Digital compliance in Canada has moved beyond basic accessibility standards into legally enforced privacy architecture. A growth-stage financial platform must adhere to multi-jurisdictional mandates that directly dictate UI layout, asset delivery, and database handling.
Implementing Quebec Law 25 Compliant Consent Architecture
Quebec's Law 25 represents the most stringent privacy legislation in North America, matching many aspects of the European General Data Protection Regulation. It strictly prohibits the use of pre-checked consent boxes, opaque tracking mechanics, and bundled terms of service. For fintech platforms operating nationally, digital interfaces must respect these technical requirements:
First, consent for analytical and marketing tracking scripts must be explicitly opted into before those tags execute. Deploying client-side tag managers that trigger tracking pixels prior to user interaction violates provincial law and creates legal exposure. Second, consent configurations must be granular. Users must be granted the interface controls to allow operational cookies while declining behavioral profiling, without sacrificing their ability to use core platform features.
Third, bilingual language parity under Bill 96 requires absolute functional and contextual equality. The French version of your digital experience cannot be a delayed, machine-translated afterthought. Navigation menus, onboarding micro-copy, dynamic legal disclosures, and error states must render in clear, native French. Failing to provide equal UI real estate for longer French translations routinely breaks responsive layouts, causing visual degradation and undermining platform trust in an essential market.
```
++
| CANADIAN REGULATORY COMPLIANCE MATRIX |
++
| JURISDICTION / ACT | CORE FRONT-END UX REQUIREMENT | TECHNICAL IMPACT |
++
| Quebec Law 25 | Granular, opt-in consent banners | Zero tracking before opt-in; |
| | with clear data use terms. | isolated analytics tags.|
++
| Accessible Canada | WCAG 2.1 Level AA compliance; | Semantic HTML, full |
| Act / AODA | high-contrast input elements. | keyboard navigation. |
++
| FINTRAC / Proceeds | Plain-language inline rationales | Dynamic input masking, |
| of Crime Act | for SIN and ID capture. | client-side encryption. |
++
| Bank of Canada RPAA | Absolute fee transparency and | Real-time fee breakdowns|
| | operational status reporting. | embedded into funnels. |
++
```
Accessibility Standards as an Operational Prerequisite
Complying with the Accessibility for Ontarians with Disabilities Act and the Accessible Canada Act requires meeting Web Content Accessibility Guidelines 2.1 Level AA standards. Financial dashboards frequently fail these baselines due to complex data tables, low-contrast text on subtle data cards, and inaccessible dynamic charts.
An accessible financial interface uses semantic HTML structure, comprehensive screen-reader landmarks, and complete keyboard navigation across complex elements like date pickers and asset allocation sliders. Input fields must retain clear, persistent focus states, and automated error states must be declared via ARIA live regions so visually impaired users are not stranded during high-stakes financial operations. Beyond legal safety, building accessible digital portals expands your market to millions of Canadians with permanent or situational disabilities, while establishing an institutional visual clarity that benefits every user.
Technical Architecture: Separating Marketing Front-Ends from Secure Financial Portals
A common technical error among early-stage financial platforms is building the public marketing website on the same codebase or infrastructure as the authenticated customer dashboard. While this seems convenient during early prototyping, it introduces severe conversion, performance, and security liabilities as the platform scales.
Mitigating Security Surface Areas via Decoupled Infrastructure
Public marketing websites require rapid iteration, frequent design updates, third-party marketing tags, and dynamic content management systems. Authenticated financial portals require zero-trust access controls, hardened Content Security Policies, absolute isolation from unvetted third-party JavaScript, and strict cross-origin resource sharing rules.
```
SECURE DECOUPLED ARCHITECTURE
[Edge Network / Global CDN]
|
+> [Marketing Site: Next.js / Static Edge] (public domain)
| - Headless CMS
| - Strict Law 25 Tag Sandboxing
| - Sub-Second Load Speeds
|
+> [Authentication Layer: Zero-Trust OAuth 2.0 / Passkeys]
|
v
[Client Portal: Isolated Web App] (secure subdomain)
- Strict Content Security Policy (CSP)
- Zero External Marketing Scripts
- Direct Encrypted Financial API Gateway
```
A sophisticated digital architecture cleanly separates these concerns across different subdomains and decoupled cloud environments. The marketing presence should operate on a modern, edge-rendered framework like Next.js, serving pre-rendered static assets across content delivery networks for sub-second performance. The secure client portal should live on an isolated, hardened infrastructure, completely walled off from third-party marketing tags that could expose sensitive customer data to cross-site scripting or formjacking vulnerabilities.
When users move from the public marketing site to the onboarding funnel, their authentication transition must be visually seamless. High-performing platforms maintain unified design systems across both environments using shared UI component libraries, identical design tokens, and smooth token-based handoffs. This prevents the jarring visual shifts that lead users to question whether they have been phished.
Speed as a Core Trust Metric in Financial Services
Page load performance directly impacts financial credibility. Financial platforms do not have the luxury of slow interfaces. If a customer is transferring ten thousand dollars or reviewing an unexpected line of credit fee, an interface that freezes or renders layout shifts causes instant panic.
Modern fintech website design in Canada demands optimizing for Core Web Vitals with absolute discipline:
- Eliminate Layout Shifts: Financial balance widgets, currency selectors, and transaction tables must use explicitly reserved layout dimensions to eliminate Cumulative Layout Shift, preventing users from clicking the wrong financial confirmation button.
- Minimize Third-Party Script Contention: Keep marketing and attribution tracking pixels outside of critical path authentication flows. Run non-essential scripts via web workers using tools like Partytown, or process analytics server-side to keep the main browser thread clear for input validation.
- Optimize Asset Delivery: Serve responsive vector icons, subset system fonts to reduce font-flicker, and pre-fetch authentication modules during the final steps of marketing landing page interactions.
When a digital platform renders in under eight hundred milliseconds on a mobile connection, it subconsciously conveys modern infrastructure, institutional efficiency, and technical competence.
Conversion Rate Optimization Frameworks for Complex Financial Workflows
Fintech conversion rate optimization does not rely on typical e-commerce tactics like countdown timers, artificial scarcity indicators, or aggressive exit popups. In financial services, those tactics look amateurish and predatory, which immediately repels discerning clients. High-converting optimization is anchored in friction reduction, cognitive reassurance, and radical pricing transparency.
The Power of Interactive Financial Utility Tools
Static landing pages rarely convert high-intent financial prospects at scale. Financial consumers are calculating, skeptical, and focused on specific personal outcomes. Replacing static copy with interactive calculators, real-time fee comparison sliders, and dynamic return simulators generates significantly higher top-of-funnel conversion rates.
```
++
| DYNAMIC BORROWING CALCULATOR WIREFRAME |
++
| [ Loan Amount Slider: $25,000 ] [ Amortization Term: 36 Months ] |
| |
| Traditional Bank Estimated Cost: Fintech Platform Transparent Cost: |
| $842/mo at 12.4% APR $731/mo at 6.8% APR |
| Total Interest: $5,312 Total Interest: $1,316 |
| |
| [ Visual Savings Delta: You save $3,996 over the loan lifespan ] |
| |
| [ BUTTON: Lock In Your Rate in 2 Minutes - Soft Credit Check Only ] |
++
```
When building an auto-loan, mortgage refinance, or automated investment tool, let prospects manipulate scenarios with real numbers. When the prospective customer sees their exact savings, their expected return, or their projected cash-flow runway calculated in real time, transition them directly into the onboarding workflow with their calculated data points pre-populated. This eliminates redundant data entry, preserves user momentum, and grounds their application in demonstrated financial value.
Systematic A/B Testing Anchored in Security and Clarity
When testing UX variations across financial flows, focus experimentation on risk-reduction variables rather than superficial elements like button colors or hero imagery:
- ✓Security Disclaimers: Test whether explicit, plain-language encryption badges near input fields outperform generic institutional security badges.
- ✓Social Proof Realism: Contrast broad marketing testimonials with verified customer case studies that feature relatable financial goals and specific milestones.
- ✓Progress Visibility: Test step-by-step progress bars that explicitly show how many steps remain in the KYC verification flow against dynamic checklist formats. Clear expectations consistently reduce onboarding drop-offs.
- ✓Credit Impact Messaging: Emphasize soft check credit pre-approvals across top-of-funnel interactions to eliminate the fear of credit score damage.
By systematically addressing latent psychological objections, product teams build resilient onboarding funnels that drive durable, long-term conversions.
Practical Business Takeaways for Fintech Leaders
Scaling a financial platform in Canada requires alignment between technical execution, UX architecture, and compliance oversight. Product managers, marketing leads, and technical founders can use this operational checklist to evaluate their digital platforms:
- Conduct a Trust and Compliance UX Audit: Review every landing page, onboarding step, and automated email. Confirm that all regulatory disclosures, whether referencing CDIC pass-through protections, CIRO memberships, or Bank of Canada registrations, reflect exact legal operating realities with zero misleading claims.
- Re-Architect Identity Verification Funnels: Decouple account creation from heavy KYC data capture. Employ progressive profiling that delivers upfront utility, and use inline, plain-language helper copy to explain why the Canada Revenue Agency or FINTRAC requires sensitive identifiers like Social Insurance Numbers.
- Harden Consent and Accessibility Systems: Verify that your marketing tracking scripts comply with Quebec Law 25 by requiring explicit user opt-ins before firing. Audit your customer-facing dashboard against WCAG 2.1 Level AA to guarantee screen-reader accessibility and maintain functional English-French bilingual parity.
- Physically Isolate Web Front-Ends from Client Portals: Maintain an architectural separation between your public marketing engine and authenticated financial portals. This prevents client-side marketing script vulnerabilities from compromising customer dashboards and preserves sub-second Core Web Vitals on your primary acquisition funnels.
- Eliminate Performance-Draining MarTech Bloat: Remove redundant tracking scripts, session recording tools on sensitive form fields, and unvalidated third-party chat widgets that degrade mobile load speeds. Treat speed as a foundational security and trust metric.
How PiTech Accelerates Compliant, High-Converting Financial Platforms
Building an enterprise-grade digital platform requires coordinating advanced technical engineering with specialized, industry-specific UX architecture. PiTech helps Canadian fintech startups, scale-ups, and established financial institutions develop digital assets that convert skeptical traffic into verified, active accounts without creating regulatory or security vulnerabilities.
Custom Software Engineering and Secure Architecture
PiTech specializes in architecting modern, resilient digital platforms engineered specifically for complex industries. Through our [custom software development services](https://pitech.ca/services/software-development), we build isolated, zero-trust client portals, engineer secure API connections with open banking aggregators like Flinks and Plaid, and construct robust, automated identity verification workflows. We architect decoupled systems that allow marketing teams to iterate freely on edge-rendered front-ends, while client dashboards remain completely protected from front-end vulnerabilities and performance degradation.
Conversion-Driven UX/UI and Digital Strategy
Friction inside a financial funnel directly inflates customer acquisition costs. Through our dedicated [UX/UI design strategy](https://pitech.ca/services/ui-ux-design) and [web design and development services](https://pitech.ca/services/web-development), PiTech reimagines onboarding flows, self-service account dashboards, and interactive financial tools. We eliminate drop-offs through progressive profiling, accessible design systems that meet WCAG 2.1 Level AA and AODA mandates, and localized, bilingual interfaces that perform reliably under Quebec's Law 25 and Bill 96.
Full-Funnel Conversion Optimization and Growth Execution
A beautiful digital presence is meaningless if user acquisition breaks down between marketing attribution and identity verification. Our [conversion rate optimization practice](https://pitech.ca/services/conversion-rate-optimization) diagnoses drop-offs across every stage of the user journey. By deploying privacy-first, server-side analytics, running targeted A/B tests, and refining data capture forms, we help financial challengers improve funnel throughput and maximize enterprise valuation. When your roadmap extends to native mobile platforms, our [mobile app development services](https://pitech.ca/services/mobile-app-development) ensure a cohesive transition from responsive web funnels into secure, biometrically authenticated iOS and Android applications.
Building a Market-Leading Financial Platform
Canadian financial consumers are discerning, risk-averse, and well-served by entrenched banking institutions. Winning market share in this climate requires proving that your platform matches institutional banks in security, stability, and legal integrity, while completely outperforming them in speed, convenience, and user experience.
Treating interface design, technical architecture, and regulatory compliance as disconnected priorities leads to high funnel abandonment, mounting acquisition costs, and increased regulatory scrutiny. By anchoring your digital footprint in radical transparency, progressive verification, and edge-rendered performance, you break through the trust barrier and build an enduring competitive advantage.
Is your financial onboarding funnel leaking qualified users, or does your customer portal need enterprise-grade modernization? Contact the engineering and UX team at PiTech to schedule a comprehensive Fintech UX and Security Architecture Audit, and build a digital foundation designed for secure, scalable conversion.
Ready to Transform Your Business?
Let PiTech help you implement these strategies with proven technology solutions.
Get StartedRelated articles
- Custom Web Design for Law Firms Canada: A Growth DriverDiscover how custom web design for law firms in Canada drives client acquisition, builds trust, and ensures legal compliance in a competitive digital market.
- Optimizing SaaS Funnels for Canadian B2B: A Growth GuideYour Canadian B2B SaaS funnel is leaking revenue. Learn advanced strategies beyond basic nurturing for SaaS sales funnel optimization in Canada. Drive growth now.
- Custom Web Design Canada: Beyond a Template to Drive ConversionsYour template website looks nice, but it isn't generating leads. Discover how custom web design in Canada helps service businesses drive real conversion and ROI.
- Canadian Data Residency Cloud Architecture: Law 25 GuideLearn why US cloud setups fail Quebec Law 25 compliance. Discover our Canadian data residency cloud architecture blueprint to secure enterprise infrastructure.